Introduction
Understanding the differences between Direct Primary Care (DPC) and traditional insurance is crucial for patients navigating their healthcare options. As healthcare models evolve, patients often find themselves faced with choices that can significantly impact their access to care, costs, and overall experience. This article delves into the nuances of DPC and traditional insurance, helping you make informed decisions about your healthcare.
What is Direct Primary Care?
Direct Primary Care (DPC) is a healthcare model where patients pay a monthly membership fee directly to their primary care provider for a range of services. This model typically covers essential primary care services, such as routine check-ups, preventive care, and chronic disease management, without the complexities of insurance claims.
One of the most significant advantages of DPC is the direct relationship between patients and providers. This model often allows for more personalized care, as patients can communicate directly with their doctors without the barriers posed by insurance companies. DPC practices may also offer extended appointment times, same-day visits, and enhanced access to care through telemedicine.
However, DPC does have limitations. It is not a substitute for comprehensive insurance, as it generally does not cover major medical events, specialist care, or hospitalization. Therefore, patients who choose DPC should consider maintaining separate insurance for these needs.
What is Traditional Insurance?
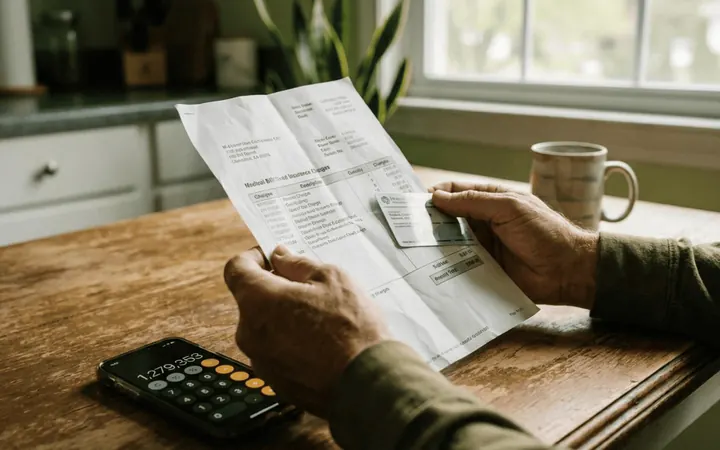
Traditional insurance is a healthcare coverage model where patients pay a monthly premium to an insurance company in exchange for financial protection against medical expenses. This model typically includes various cost-sharing mechanisms, such as deductibles, copays, and coinsurance.
Key terms to understand in traditional insurance include:
- Premium: The monthly amount paid for insurance coverage.
- Deductible: The amount a patient must pay out-of-pocket before insurance begins to cover costs.
- Copay: A fixed fee paid by the patient for specific services, such as doctor visits or prescriptions.
- Coinsurance: The percentage of costs the patient is responsible for after meeting the deductible.
- Covered service: Medical services that the insurance plan will pay for.
Traditional insurance plans can provide comprehensive coverage, including access to a wide range of healthcare services, specialists, and hospitals. However, they can also involve complex networks, prior authorizations, and potential out-of-pocket costs that can add up quickly.
Cost Comparison
When comparing DPC and traditional insurance, costs are a significant factor. Here’s a breakdown of the different expenses associated with each model:
Direct Primary Care Costs
In a DPC model, patients typically pay a monthly membership fee that can range from $50 to $150 per month, depending on the provider and the services included. This fee often covers:
- Routine office visits
- Preventive care
- Chronic disease management
- Telemedicine services
However, patients should be aware that DPC does not cover specialist visits, hospitalizations, or emergency care, which means additional costs may arise if such services are needed.
Traditional Insurance Costs
Traditional insurance involves a more complex cost structure:
- Premiums: Monthly premiums can vary widely based on the plan and coverage level, often ranging from $200 to $600 or more for individuals.
- Deductibles: Many plans have deductibles that can range from $1,000 to $6,000 or more, meaning patients must pay this amount out-of-pocket before insurance coverage kicks in.
- Copays and Coinsurance: After meeting the deductible, patients may still pay copays or a percentage of the costs for services.
While traditional insurance can provide comprehensive coverage, the potential for high out-of-pocket costs can be a significant concern for many patients.
Coverage Differences
Understanding what is covered under each model is crucial for making informed decisions.
What DPC Typically Covers
DPC primarily focuses on primary care services, which may include:
- Annual wellness exams
- Vaccinations
- Basic lab tests
- Management of chronic conditions
- Minor procedures
- Telehealth visits
However, DPC does not typically cover:
- Specialist consultations
- Emergency room visits
- Hospital stays
- Major surgeries
What Traditional Insurance Typically Covers
Traditional insurance plans often provide more comprehensive coverage, including:
- Primary care and specialty visits
- Emergency care
- Hospitalization
- Prescription medications
- Maternity care
- Preventive services
This comprehensive coverage can be beneficial for those who may require more extensive medical care, though it often comes with higher costs and complex networks.
Patient Experience
The patient experience can vary significantly between DPC and traditional insurance models.
Access to Care in DPC
Patients in a DPC model often enjoy:
- Direct access to their primary care provider without the need for referrals.
- Longer appointment times and more personalized care.
- Flexible scheduling, including same-day appointments and telehealth options.
This model can foster stronger relationships between patients and providers, leading to better overall satisfaction.
Access to Care in Traditional Insurance
In traditional insurance models, patients may experience:
- Network restrictions, requiring patients to choose from a list of in-network providers.
- Referral requirements for specialist visits, which can delay access to necessary care.
- Variable appointment availability depending on provider schedules.
These factors can sometimes lead to frustration and delays in receiving care.
Eligibility Requirements
Eligibility for DPC and traditional insurance can differ significantly.
DPC Eligibility
DPC models generally have fewer restrictions. Most patients can enroll in a DPC practice as long as they pay the monthly membership fee. However, some practices may have specific age or health restrictions based on their patient population.
Traditional Insurance Eligibility
Eligibility for traditional insurance can involve more complexities, including:
- Open enrollment periods, during which individuals can sign up for coverage.
- Potential exclusions for pre-existing conditions, depending on the plan.
- Eligibility for subsidies or tax credits based on income and household size.
Understanding these eligibility criteria is essential for patients considering their options.
Tradeoffs to Consider
Choosing between DPC and traditional insurance involves weighing several tradeoffs:
- Cost: DPC typically has lower monthly costs compared to traditional insurance premiums. However, patients may face higher out-of-pocket expenses for specialty care and emergencies.
- Access to Care: DPC offers direct access to primary care but may lack coverage for specialists. Traditional insurance provides comprehensive coverage but can involve network restrictions and referral requirements.
- Personal Relationships: DPC fosters closer relationships with providers, while traditional insurance may lead to more transactional interactions due to the volume of patients.
Considering these tradeoffs can help patients align their healthcare choices with their needs and preferences.
Common Mistakes to Avoid
When considering DPC or traditional insurance, patients often make several common mistakes. Here are some to be aware of:
- Assuming DPC is Comprehensive: Some patients mistakenly believe that DPC can replace traditional insurance entirely. It is important to understand that DPC does not cover major medical events or hospitalizations.
- Neglecting to Consider Out-of-Pocket Costs: While DPC may have lower monthly fees, patients should account for potential costs related to specialist visits and emergencies that are not covered by DPC.
- Overlooking the Importance of Provider Networks: In traditional insurance, being out-of-network can lead to higher costs. Patients should verify which providers are in-network to avoid unexpected expenses.
- Ignoring Eligibility Criteria: Patients may overlook eligibility requirements for both DPC and traditional insurance, which can lead to complications when trying to enroll.
Verification Guidance
Before making a decision, it is crucial to verify details with providers and insurance plans. Here are some steps to take:
- Contact DPC Practices: Inquire about the specific services included in the membership fee and any additional costs for services not covered.
- Review Insurance Policies: Carefully read the policy documents to understand coverage limits, exclusions, and any potential out-of-pocket costs.
- Check Provider Networks: Verify which providers are in-network for traditional insurance plans to ensure access to preferred doctors.
- Ask About Eligibility: Confirm eligibility criteria for both DPC and traditional insurance to avoid complications during enrollment.
Practical Checklist for Decision-Making
Here is a practical checklist to guide your decision-making process:
- What services are included in the membership fee for DPC?
- How much will I pay out-of-pocket for specialist visits or emergency care?
- What are the monthly premiums and deductibles for traditional insurance?
- Are there any hidden costs associated with either option?
- How easily can I access my primary care provider in both models?
- What are the eligibility requirements for DPC and traditional insurance?
- How does each option align with my healthcare needs and budget?
- What are the potential trade-offs between lower costs and comprehensive coverage?
Real-Life Scenarios
To illustrate the differences between DPC and traditional insurance, here are two real-life scenarios:
Scenario 1: A Young Professional
A young professional, Alex, is considering DPC for primary care. Alex finds a DPC practice that charges $100 per month. This fee covers all primary care visits, routine lab tests, and telehealth services. However, Alex is concerned about coverage for potential emergencies or specialist visits, which would require additional insurance.
In contrast, Alex also explores traditional insurance options, where the monthly premium is $300 with a $2,000 deductible. While this plan covers emergencies and specialists, Alex worries about the higher monthly costs and the potential for high out-of-pocket expenses.
Scenario 2: A Family with Children
A family with children, the Johnsons, evaluates DPC for preventive care and traditional insurance for emergencies. They find a DPC practice that offers a family membership for $250 per month, which includes all routine visits and vaccinations. However, they realize that if a family member requires emergency care, they would need separate insurance coverage, which could be an additional $500 per month.
On the other hand, traditional insurance offers a family plan with a $400 premium and a $1,500 deductible, providing comprehensive coverage for emergencies and specialist visits. The Johnsons must weigh the benefits of preventive care in DPC against the security of comprehensive coverage in traditional insurance.
How Choices Ahead Can Help
At Choices Ahead, we understand that navigating healthcare options can be overwhelming. Our education-first platform provides resources to help you compare DPC and traditional insurance. We offer tools to:
- Understand the key differences between healthcare models.
- Compare monthly costs, coverage options, and eligibility requirements.
- Identify tradeoffs and what to consider before making a decision.
- Find providers and plans that fit your specific needs.
Whether you are leaning towards DPC for personalized care or traditional insurance for comprehensive coverage, visit Choices Ahead to explore your options and make an informed choice.
Conclusion
Choosing between Direct Primary Care and traditional insurance is a significant decision that can affect your healthcare experience and costs. By understanding the differences in costs, coverage, patient experience, and eligibility, you can make an informed choice that aligns with your healthcare needs. Remember to ask the right questions and utilize resources like Choices Ahead to guide you through the process. Your healthcare journey is important, and being informed is the first step towards making the best choice for you and your family.
Explore your healthcare options today.
Review the next step and explore the information that may help you move forward.