Introduction
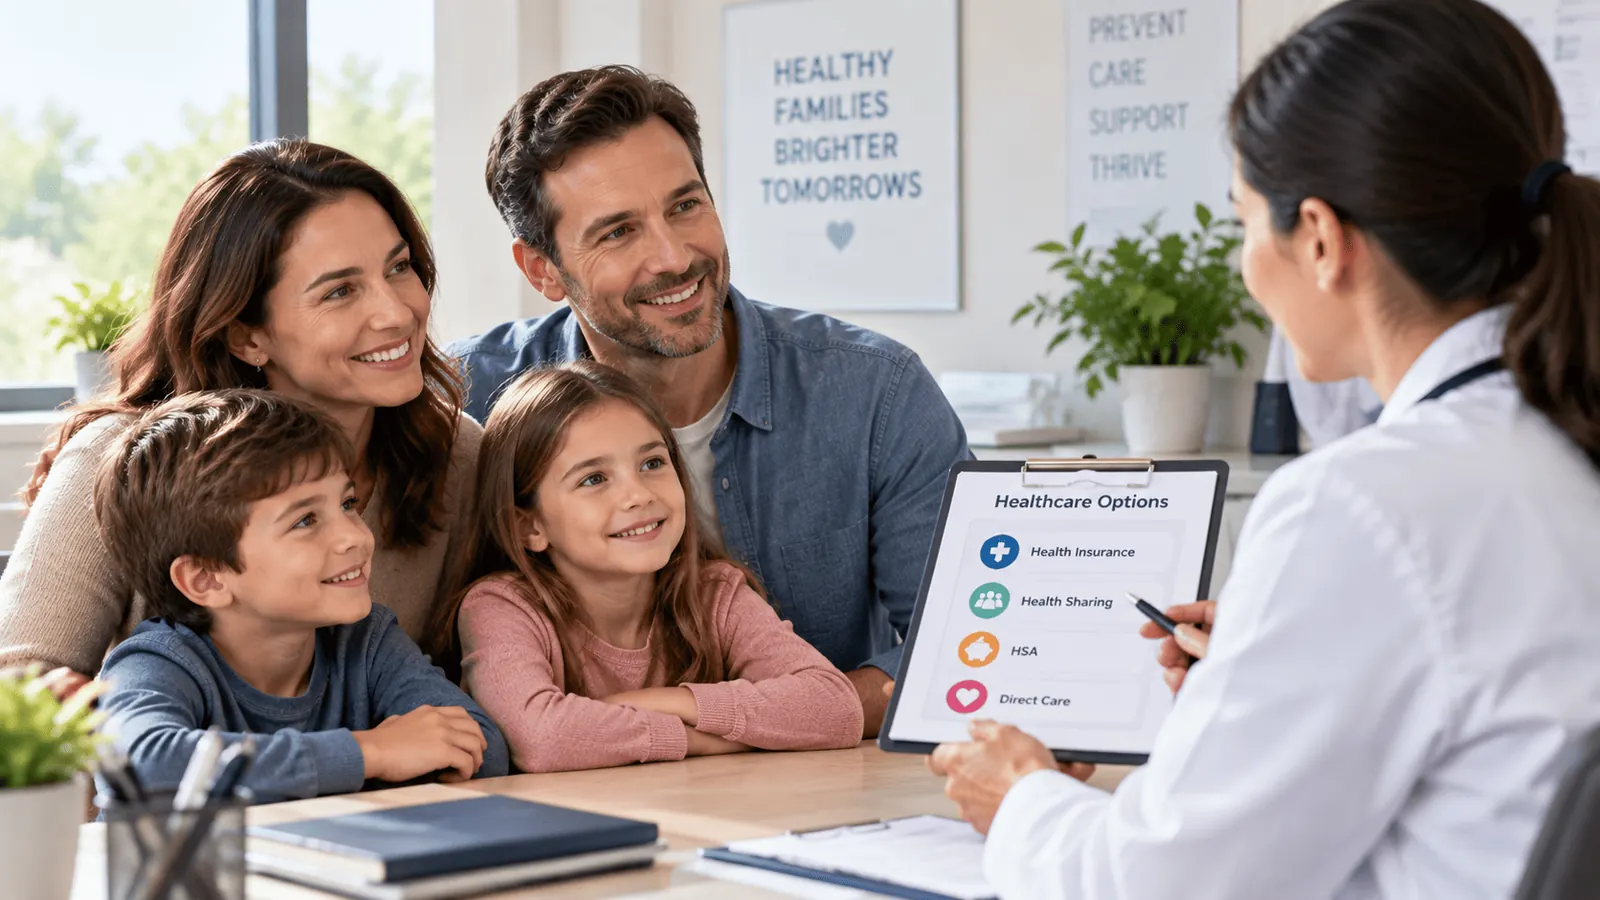
Understanding your family's healthcare options is crucial for making informed decisions about coverage that fits your unique needs. With numerous models available, including traditional insurance, health sharing, crowdfunding, and direct primary care, families often find themselves confused about the best path forward. This guide aims to illuminate the questions you should ask when evaluating these options, helping you navigate the complexities of healthcare and make choices that best serve your family.
Overview of Healthcare Options
Before diving into the questions to ask, it is essential to understand the variety of healthcare options available for families. Each option comes with its own set of rules, benefits, and limitations.
1. Traditional Insurance
Traditional insurance typically involves paying a premium for coverage that includes a range of services. Key features include:
- Premium: The monthly cost you pay for your insurance policy.
- Deductible: The amount you have to pay out-of-pocket before your insurance starts to cover expenses.
- Copay: A fixed amount you pay for a specific service at the time of care.
- Coinsurance: The percentage of costs you share with your insurance after meeting your deductible.
Traditional insurance often provides comprehensive coverage and protections for pre-existing conditions, particularly under ACA-compliant plans. This means that if you have a health condition that existed before your coverage begins, your insurance cannot deny you coverage or charge you more for it.
2. Health Sharing
Health sharing is a community-based approach where members contribute monthly to share in each other's medical costs. This model does not function as insurance and has specific eligibility and sharing guidelines. Key terms include:
- Initial Unshareable Amount (IUA): The amount members are responsible for before sharing begins.
- Member Responsibility: The total amount a member must cover for their own medical expenses.
- Eligible for Sharing: Not all expenses may qualify for sharing, and members are responsible for verifying eligibility.
Health sharing can provide lower monthly costs, but it also comes with risks, such as no guaranteed payment for services. This means that if you have a medical expense, you may still be responsible for paying it out of pocket if it does not meet the criteria for sharing.
3. Crowdfunding
Crowdfunding involves raising money from a community or network to cover medical expenses. Members typically pay an advocacy fee to participate. Important aspects include:
- Advocacy Fee: A monthly fee paid to be part of the crowdfunding community.
- Crowdfunding Contribution: The amount raised for a specific health event, which is not guaranteed.
- Member Commitment: The amount a member agrees to contribute towards a specific health event.
This model can be beneficial for specific needs but lacks the protections and guarantees associated with traditional insurance. For example, if you have a significant medical event, the amount raised through crowdfunding may not fully cover your expenses.
4. Direct Primary Care
Direct primary care (DPC) is a model where patients pay a recurring membership fee directly to a primary care provider for access to a range of services. Key features include:
- Recurring Membership Fee: The monthly cost paid directly to the provider.
- Services Covered: Typically includes primary care services, but hospitalization and specialty care may not be included.
- Access to Care: Often provides greater access to the provider and may include virtual care options.
DPC can offer personalized care and convenience but does not replace comprehensive insurance coverage for more significant health events. It is important to note that if you need specialized treatment or hospitalization, you may still require additional insurance coverage.
Key Questions to Ask When Evaluating Healthcare Options
When evaluating healthcare options for your family, asking the right questions can lead to better decision-making. Below are essential inquiries to consider:
1. What are the monthly costs associated with each healthcare option?
Understanding the financial commitment is crucial. Inquire about:
- Monthly premiums or contributions.
- Additional fees, such as copays or advocacy fees.
- Potential penalties for not meeting obligations, especially in health sharing or crowdfunding models.
Example: A family of four considering a health sharing plan should clarify their monthly contributions and any additional costs related to specific health events. If a health sharing community charges $905 per month for a family, it is essential to understand what services are included and what out-of-pocket expenses might arise.
2. How do I determine which services are covered and which are not?
Healthcare options can vary widely in terms of coverage. Key points to ask include:
- What specific services are included in the plan?
- Are there any exclusions or waiting periods for certain services?
- How are pre-existing conditions treated?
Example: A single parent evaluating direct primary care for their child should ask about virtual care services and what additional costs may arise for specialist referrals. Knowing what is covered can help avoid unexpected bills.
3. What are the eligibility requirements for joining a specific plan?
Eligibility can vary significantly between plans. Questions to ask include:
- Are there age limits, residency requirements, or lifestyle restrictions (e.g., tobacco use)?
- What documentation is needed to enroll?
- Are there waiting periods for certain services or conditions?
Understanding eligibility helps avoid surprises down the line. For instance, some health sharing organizations may have restrictions based on age or pre-existing conditions, which can affect your ability to enroll.
4. What questions should I ask about pre-existing conditions?
Pre-existing conditions can complicate coverage. Important questions include:
- How does the plan define a pre-existing condition?
- What are the waiting periods before coverage kicks in for existing issues?
- Are there any limits on coverage for pre-existing conditions?
Clarifying these points can prevent unexpected costs and ensure adequate coverage. For example, if you have a chronic condition, knowing how long you must wait before receiving coverage can help you plan accordingly.
5. How can I verify the claims made by a healthcare provider?
Verification is crucial to ensure that the information provided is accurate. Consider asking:
- What resources are available to verify coverage and costs?
- Can I access reviews or testimonials from other members?
- How often are the plan details updated, and where can I find the most current information?
Being proactive in verification can save time and resources in the long run. For instance, checking online reviews or asking current members about their experiences can provide valuable insights into the reliability of a plan.
Understanding Costs and Coverage
When comparing healthcare options, understanding the nuances of costs, coverage, and eligibility is essential. Here are some steps to guide you:
- Compare Monthly Costs: Look beyond the premium or contribution amounts. Factor in additional costs like deductibles, copays, and out-of-pocket maximums.
- Evaluate Coverage: Create a checklist of services your family needs and see how each option meets these needs. For example, if your family requires regular pediatric care, ensure that the chosen plan covers those visits adequately.
- Assess Eligibility: Ensure you understand the eligibility rules for each plan and how they may affect your family's situation. This includes understanding any lifestyle requirements that may restrict enrollment.
This comprehensive comparison will help you make an informed decision that aligns with your family's healthcare needs and budget.
Tradeoffs and Risks in Healthcare Options
Every healthcare model comes with its own set of tradeoffs and risks. Understanding these can help you make a better choice:
- Lower Monthly Costs vs. Higher Out-of-Pocket Expenses: Health sharing and crowdfunding may offer lower monthly contributions but can lead to higher out-of-pocket costs in case of a health event. For instance, if you have a significant medical need, you may end up paying more out of pocket than you would with traditional insurance.
- Flexibility in Provider Choice vs. Limited Coverage: Direct primary care may offer more personalized care, but you might have limited options for specialist referrals or hospitalizations. This could be a disadvantage if your family requires specialized care.
- Potential Lack of Guaranteed Payment: Unlike traditional insurance, health sharing does not guarantee payment for services, which can leave members financially exposed. If a medical expense is deemed ineligible for sharing, you may be responsible for the entire cost.
Recognizing these tradeoffs is crucial in selecting the right healthcare option for your family.
Verification Steps for Informed Decisions
To ensure that you are making informed decisions about your family's healthcare, follow these verification steps:
- Research Provider Guidelines: Always check the latest provider guidelines and official documents to verify claims made about coverage and costs. This ensures that you have the most accurate information.
- Utilize Online Resources: Look for independent reviews and testimonials from other members to understand their experiences. Websites and forums can provide insights into how well a plan operates.
- Consult with Professionals: If in doubt, consider speaking with a healthcare advocate or professional who can provide insights into specific plans. They can help clarify complex terms and conditions.
Taking these steps will help you verify the information and make more informed decisions.
How Choices Ahead Helps Families Navigate Healthcare Options
Choices Ahead is dedicated to providing families with the resources and tools necessary to navigate healthcare options effectively. Here’s how we assist:
- Compare Options: Our platform allows you to compare different healthcare options side by side, helping you identify what works best for your family.
- Understand Tradeoffs: We explain the tradeoffs associated with each model, providing you with the information needed to weigh your options carefully.
- Browse Providers: Access detailed profiles of various healthcare providers, including pricing notes, eligibility rules, and service areas.
- Ask Better Questions: We offer practical questions to consider when evaluating plans, empowering you to make informed choices.
By equipping families with clear information and resources, Choices Ahead aims to simplify the decision-making process and help you find the healthcare option that fits your needs.
Conclusion
Choosing the right healthcare option for your family is a significant decision that requires careful consideration and understanding of various factors. By asking the right questions and utilizing the resources available through Choices Ahead, you can navigate the complexities of healthcare options with confidence. Remember, the key to making informed decisions lies in understanding costs, coverage, eligibility requirements, and verifying the information provided by healthcare providers.
To explore healthcare options that fit your family's needs and start comparing today, visit Choices Ahead and take the first step towards making informed healthcare decisions.
Find the healthcare option that fits your family.
Review the next step and explore the information that may help you move forward.