Introduction
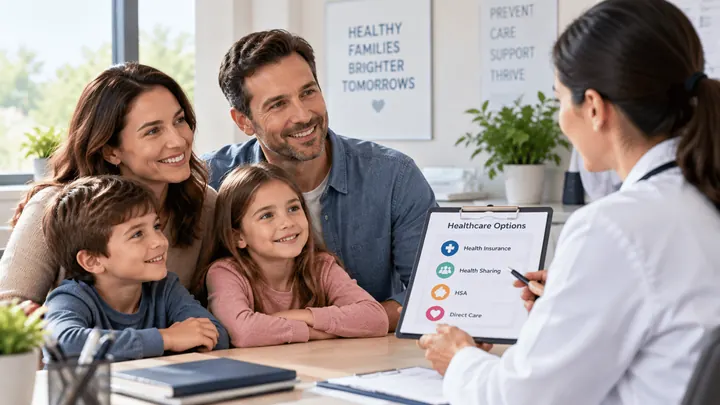
Families with children often face unique healthcare needs and challenges. While traditional health insurance is a common choice, many families are turning to healthsharing as an alternative. Healthsharing offers a community-based approach to managing healthcare costs, but it operates differently from traditional insurance. Understanding how healthsharing works, what to verify before selecting a plan, and how it compares to conventional insurance is crucial for making informed decisions. This article will explore the specifics of healthsharing for children's healthcare, empowering families to make choices tailored to their needs.
What is Healthsharing?
Healthsharing is a community-based model where members share medical expenses instead of paying premiums to an insurance company. Unlike traditional insurance, healthsharing organizations do not guarantee payment for medical expenses. Instead, they facilitate a system where members contribute monthly to a pool that can be used to cover eligible medical expenses incurred by other members.
This model operates on the principle of mutual aid, where members agree to share each other's medical costs. Healthsharing can provide flexibility in terms of provider choice and often comes with lower monthly costs compared to traditional insurance. However, it also carries certain risks, such as potential unpredictability in out-of-pocket expenses.
How Healthsharing Differs from Traditional Insurance
To better understand healthsharing, it is essential to distinguish it from traditional insurance. Here are some key differences:
- Coverage Guarantees: Traditional insurance guarantees payment for covered services, while healthsharing does not guarantee payment for any medical expense.
- Cost Structure: Healthsharing often has lower monthly contributions compared to insurance premiums, but members may face higher out-of-pocket expenses if unexpected medical needs arise.
- Provider Access: Traditional insurance usually has a network of providers, whereas many healthsharing organizations allow members to choose their providers freely.
- Eligibility Requirements: Healthsharing organizations often have lifestyle and health requirements that members must adhere to, which may not be present in traditional insurance.
Eligibility for Healthsharing
When considering healthsharing for children, it's crucial to understand the eligibility requirements. Each healthsharing organization has its own guidelines, but generally, children can be included in a family membership. Here are some common eligibility criteria:
- Age Limits: Some organizations may have age restrictions for children, often allowing coverage up to a certain age, such as 26 years.
- Health Status: Pre-existing conditions may affect eligibility. Most healthsharing organizations have waiting periods for certain medical conditions.
- Membership Guidelines: Families must adhere to the organization's lifestyle guidelines, which may include abstaining from tobacco or excessive alcohol consumption.
Before enrolling, families should carefully review the healthsharing organization’s guidelines to ensure their children qualify for coverage.
Common Healthcare Needs for Children
Children have unique healthcare needs that differ from adults. Some common healthcare needs for children include:
- Routine Check-Ups: Regular check-ups are essential for monitoring growth and development.
- Vaccinations: Immunizations are critical for preventing diseases and are often required for school entry.
- Emergency Care: Accidents and sudden illnesses can necessitate emergency medical attention.
- Chronic Conditions: Conditions such as asthma or allergies may require ongoing management and treatment.
Healthsharing can address these needs, but families should verify which specific services are eligible for sharing under their chosen plan.
Financial Responsibilities
Understanding the financial aspects of healthsharing is crucial for families. Here are the key financial responsibilities associated with healthsharing:
- Monthly Contributions: Members contribute a set amount each month, which can be lower than traditional insurance premiums. For example, a family of four might expect to pay around $905 per month.
- Initial Unshareable Amount (IUA): This is the amount a member is responsible for before expenses are eligible for sharing. The IUA can vary based on the healthsharing organization and chosen plan.
- Out-of-Pocket Costs: Members remain responsible for any unpaid medical bills. This means that if a medical expense is not eligible for sharing, the family must cover it entirely.
Families should carefully evaluate their expected healthcare needs against the financial responsibilities of the healthsharing plan to ensure it aligns with their budget.
Verification Steps Before Enrollment
Before enrolling in a healthsharing plan, families should take several verification steps:
- Review Current Guidelines: Each healthsharing organization has specific eligibility rules and guidelines. Families should review these documents to understand what is covered and what is not.
- Check for Exclusions: Certain services may be excluded from sharing, such as cosmetic procedures or experimental treatments. Understanding these exclusions can prevent unexpected costs.
- Clarify Financial Responsibilities: Families should confirm the monthly contributions, IUA, and any other costs associated with the plan.
- Inquire About Provider Access: Ensure that preferred healthcare providers are accessible under the healthsharing plan.
Taking these steps can help families avoid surprises and ensure they choose a plan that meets their children's healthcare needs.
Real-Life Examples of Healthsharing
Scenario 1: Routine Check-Ups and Vaccinations
A family of four is considering healthsharing to cover their children's routine check-ups and vaccinations. They compare various healthsharing organizations based on monthly contributions and member responsibilities. After reviewing the options, they find that one organization offers a monthly contribution of $905, which is lower than their current insurance premium. However, they also discover that the organization has a $500 IUA for each eligible medical event, meaning they would have to cover that amount before any expenses are shared.
Scenario 2: Unexpected Medical Expenses
Another family faces unexpected medical expenses when their child requires emergency care after an accident. They are enrolled in a healthsharing plan with a $1,250 IUA. After the family pays the IUA, they submit the medical bills for sharing. However, they realize that they need to verify that the emergency care is considered eligible for sharing under their plan. This experience highlights the importance of understanding what is covered and the verification process before enrolling.
Common Mistakes to Avoid When Choosing Healthsharing
Families considering healthsharing should be aware of common mistakes that can lead to unexpected challenges:
- Assuming All Medical Expenses Are Covered: Unlike traditional insurance, not all medical expenses may be eligible for sharing. Families should carefully review what is included in their plan.
- Ignoring Eligibility Requirements: Failing to understand the eligibility criteria can result in denied sharing requests. Families should ensure they meet all health and lifestyle guidelines.
- Neglecting to Verify Provider Access: Some healthsharing plans may have limitations on which providers can be used. Always check if your preferred doctors and hospitals are included.
Checklist for Choosing a Healthsharing Plan
To assist families in making informed decisions, here is a practical checklist to consider when evaluating healthsharing options:
- Review the organization's eligibility requirements and guidelines.
- Understand the financial responsibilities, including monthly contributions and IUA.
- Verify which medical expenses are eligible for sharing.
- Check for any exclusions that may apply to your family's needs.
- Inquire about provider access and whether your preferred healthcare providers are included.
- Consider the organization's track record and member satisfaction ratings.
- Evaluate how the healthsharing model aligns with your family's healthcare philosophy and lifestyle.
Conclusion
Healthsharing can be a viable alternative to traditional insurance for families seeking to manage their children's healthcare costs. However, it is essential to understand how healthsharing works, what to verify before enrolling, and the potential tradeoffs involved. Families should consider their specific healthcare needs, financial responsibilities, and eligibility requirements before making a decision.
How Choices Ahead Helps Families Navigate Healthsharing
At Choices Ahead, we provide an education-first approach to understanding healthsharing and its implications for families. Our platform helps readers compare healthcare options, understand tradeoffs, and decide what to verify before enrolling in a healthsharing plan. Families can explore various healthsharing organizations, evaluate their guidelines, and find the best fit for their needs.
To assist families further, we offer tools and resources to help you:
- Find what fits based on your budget and care needs.
- Compare options side by side.
- Browse providers to understand access and eligibility.
- Learn more about healthsharing in plain language.
Visit Choices Ahead to explore healthcare options that fit your family's needs and budget.
Explore healthcare options that fit your family's needs and budget.
Review the next step and explore the information that may help you move forward.